Event liability insurance, often called organizer liability insurance, covers third-party claims if someone is injured or property is damaged at your event. It reviews every claim, defends against unjustified ones, and pays the justified ones. It becomes necessary as soon as a private party becomes an event—i.e., when there is an admission fee, beverage service, a stage, an open guest list, or a public venue. It is available as a one-off policy for a single event or as an annual policy for clubs and companies with multiple events, with premiums based on visitor numbers, event type, venue size, and program.

At a glance
Event liability insurance, often called organizer liability insurance, covers third-party claims if someone is injured or property is damaged at your event. It reviews every claim, defends against unjustified ones, and pays the justified ones. It becomes necessary as soon as a private party becomes an event—i.e., when there is an admission fee, beverage service, a stage, an open guest list, or a public venue. It is available as a one-off policy for a single event or as an annual policy for clubs and companies with multiple events, with premiums based on visitor numbers, event type, venue size, and program.
An event can be perfectly organized and still face financial ruin within minutes. The trigger is rarely a spectacular accident, but rather a chain of minor incidents: a cable duct that isn't flush with the floor, a door left open, or a corner that becomes a bottleneck in a crowd.
We rent out event technology and do not sell insurance. Therefore, this is not a rate recommendation, but a guide to the key questions: what the coverage provides, when you need it, whether to choose a single-event or annual policy, and what factors influence the premium.
Event liability insurance is a liability policy for a single event or for all events held within a year. It covers third-party compensation claims arising from your role as an organizer: personal injury, property damage, and the resulting financial losses.
Organizer liability insurance and event liability insurance refer to the same thing. The terms only differ in whether the person or the event is in the name. Insurers use both, though you will usually find "organizer liability insurance" in the policy terms. It makes no difference to the coverage provided.
Insurance coverage begins with responsibility. Anyone who allows people onto a site bears a liability risk for those individuals, regardless of whether insurance is in place. Under Section 823 of the German Civil Code (BGB), your liability is unlimited, potentially extending to your personal assets. A serious personal injury can quickly reach millions in damages, and that is what determines the risk, not a knocked-over partition wall. Liability arises from responsibilities, contracts, and traffic safety obligations. A club is just as liable as an agency or a private individual as soon as they act as an organizer and assume duties. The venue does not automatically assume liability for everything on the premises, and service providers are only liable for their specific scope of work, which is often vaguely defined in practice.
The cases that actually occur are unspectacular. That is precisely why they are underestimated, and that is exactly what leads to compensation claims that can break a budget.
| Type of claim | Typical scenario | Why it gets expensive |
|---|---|---|
| 🚑 Personal injury | A guest trips over a cable bridge and breaks their wrist | Medical treatment, loss of earnings, claims spanning years |
| 💥 Property damage | A spotlight tips over onto parquet flooring, a drink spills over someone else's mixing console | Banal in its occurrence, expensive to replace |
| 🏛️ Rental property damage | Helpers damage a door frame in rented premises while carrying equipment | Damage to rooms and buildings is not included in every policy |
| 🍺 Serving drinks | A guest slips on spilled beer in front of the bar | Serving drinks increases risk and premiums |
| 📉 Financial loss | Damaged equipment shuts down venue operations for two days | Consequential costs exceeding the actual property damage |
Five scenarios that happen regularly. None of them are exceptional events.
Insurance doesn't prevent accidents. It prevents an accident from becoming a threat to your livelihood. The core purpose is therefore not just to pay for everything, but to assess claims: verify, defend, pay. Defending against unjustified claims acts like passive legal protection and is often underestimated. In the event of a dispute, communication with lawyers is handled through the insurer.
Common exclusions that many overlook. Pyrotechnics, drone flights, motorsports, and particularly high-risk structures are almost never included by default and require explicit coverage. Also tricky are damages resulting from intent or gross negligence, such as when required safety barriers are ignored. These are the most common reasons for an insurer to reduce benefits. You should report such additional risks early; otherwise, you lack protection exactly where the risk is highest. Conversely, some things are broader than expected: environmental damage and rental property damage to rooms and buildings are already included in some policies.
Helpers are a topic of their own. Many policies include helpers, but not in every phase. Setup and teardown should be explicitly mentioned. If helpers are considered vicarious agents, their mistakes are attributed to you. For volunteers, a written list of roles is often sufficient. Make sure to get written confirmation that your helpers are covered.
Anyone acting as an organizer and hosting visitors. The difficult question is not whether you need it, but at what point a party is considered an event.

For a private birthday party, your existing personal liability insurance usually provides coverage. However, for a wedding involving a rented venue, multiple service providers, and setup assistants, the situation is different—and this is precisely where people most often misjudge the risks. Many personal liability policies exclude organized events that involve an audience and setup.
For private organizers, there are specific policies available, often called private event liability insurance, which can be taken out for a single event. If you are planning a wedding with your own equipment and setup, you should clarify this with your insurer before signing the contract with the venue.
For associations, this is a particularly sensitive issue because, in a worst-case scenario, it is not just the association's funds that are at risk. Board members can be held personally liable for breaches of duty. Whether it is a summer festival, a tournament, or a Christmas market stall, the association acts as the organizer and thus assumes the duty to ensure public safety for the entire site.
First, check your existing association liability insurance. Some policies already include association events, though often only up to a certain number of visitors and without the sale of alcohol. You only need separate event liability insurance for associations once you exceed those limits. The gap in between is where association events frequently fall.

Companies and organizations often have this covered under their general business liability insurance, but usually only for events related to their standard business activities. A summer party with a stage, alcohol service, and external guests is generally no longer covered, nor are trade fairs or client events at an external venue. Check your existing contract before taking out a second policy.
Both are available, and the decision depends solely on the number of events you hold per year, not on the number of visitors or participants per event.
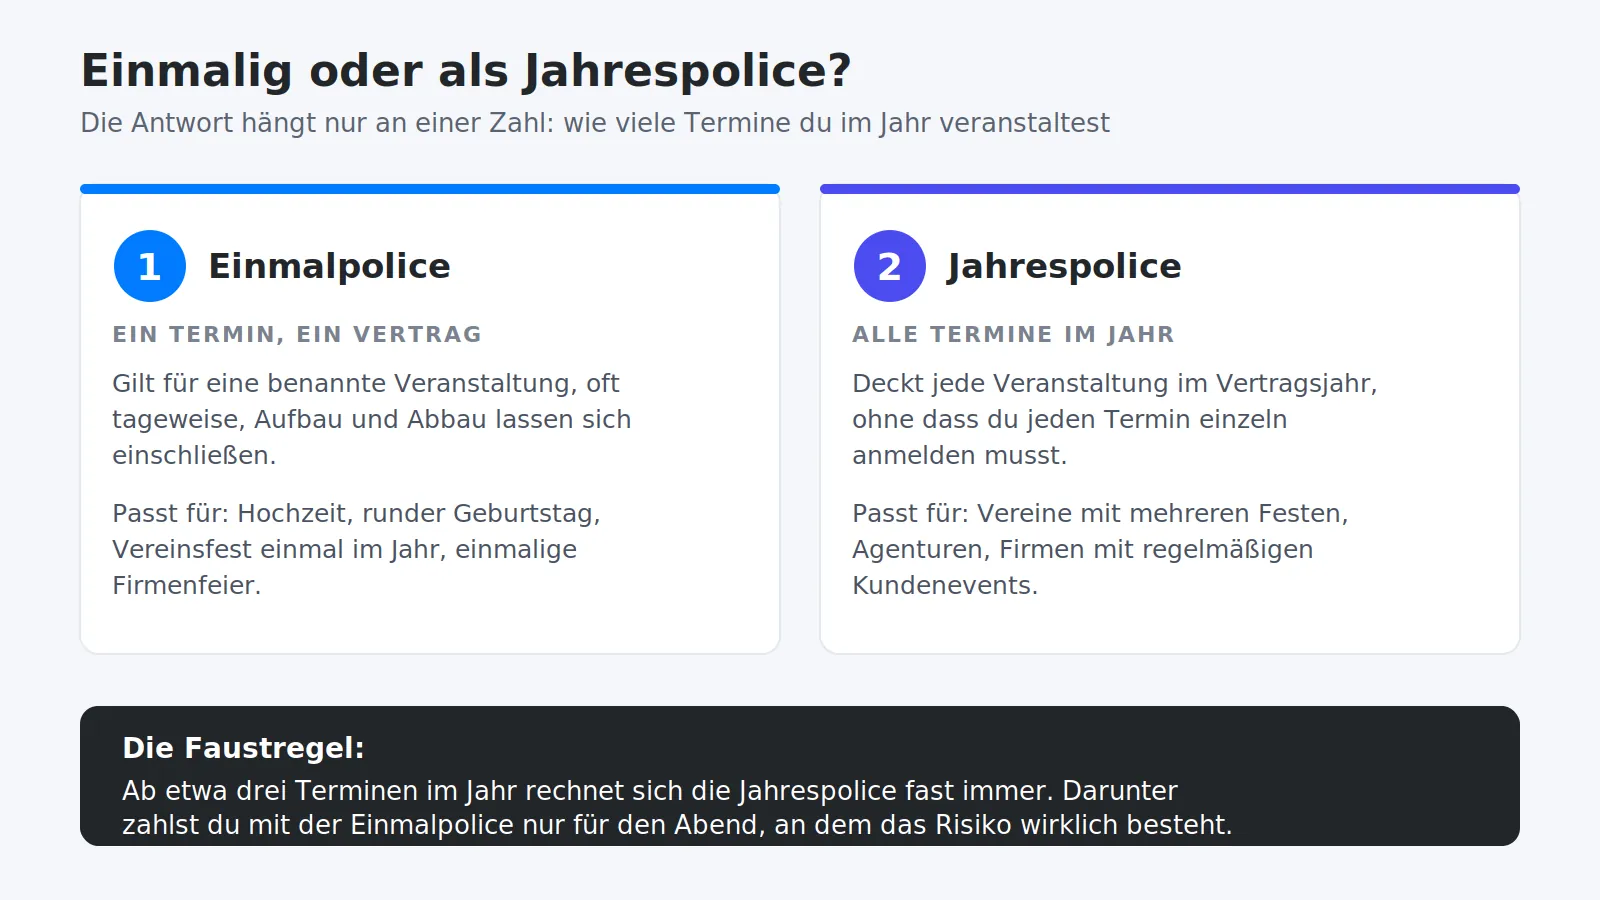
A one-off policy applies to a specific event, often on a daily basis, and can usually be taken out shortly before the date. It is important to explicitly include setup and dismantling, as otherwise, the event coverage in the contract may only begin when the first guest arrives.
An annual policy covers every event during the contract year without you having to register each date individually. This is the simpler option for associations with multiple festivals, agencies, and companies that host regular client events.
Providing a flat rate would be unprofessional because every insurer evaluates risks differently. Consequently, costs for comparable events can vary significantly. What you can know in advance are the factors that drive premiums and coverage limits.
Underinsurance is less often caused by a sum that is too low than by an incorrect description. If a small party effectively turns into a street festival, the application no longer matches reality. Check your details against the actual plan and only compare quotes based on the same assumptions.
Do you need your own policy? Three details, and you'll see what it boils down to in your case.
Who is hosting?
Who is attending?
Admission, bar service, or a stage?
| Policy | What it covers |
|---|---|
| Event liability insurance | Third-party claims related to your event; setup and teardown only if agreed upon |
| Personal liability insurance | Everyday risks; usually does not cover organized events with helpers and an audience |
| General liability insurance | Corporate events as part of standard operations; special risks require an add-on |
| Event cancellation insurance | Covers your own financial loss in the event of cancellation; liability insurance does not cover this |
| Equipment insurance | Covers damage to the equipment itself, not the consequences for third parties |
How these components work together is explained in the overview of event insurance.
Event cancellation is the component most frequently confused with liability insurance. It reimburses your own losses, not damages incurred by a guest. Only when combined do they form the event insurance policy that many people mean when they talk about coverage.
Rented event technology follows its own logic. Liability insurance protects third parties, not the rented equipment. Whether damage to equipment—including operator error, transport, and theft—is covered depends on the rental terms. At Renty, all-risk insurance is included in the rental, but this does not replace your own liability insurance for damages to third parties.
These points determine whether the policy will actually provide coverage in the event of a claim.
How the insurance process fits into the rest of your workflow is explained in the event planning guide.
What is event liability insurance?
When do you need event liability insurance?
Is event liability insurance available for a single day?
Do clubs and associations need their own event liability insurance?
Is personal liability insurance enough for a wedding?
How much does event liability insurance cost?
Check event equipment, book in 90 seconds, and choose pickup or delivery. Deposit-free and insured throughout Germany and Austria.

Wir haben dir eine Mail geschickt, bitte bestätige sie um den Rabattcode zu erhalten.